
Whether you’re buying your first home in Burquitlam, refinancing a family home on Westwood Plateau, or weighing investment property options on Burke Mountain, I can help. Coquitlam is my home base, so I know these neighbourhoods and the lenders that work best for them. I offer personalized mortgage solutions built on real lender knowledge and a focus on helping you decide with confidence.
Learn more about me →
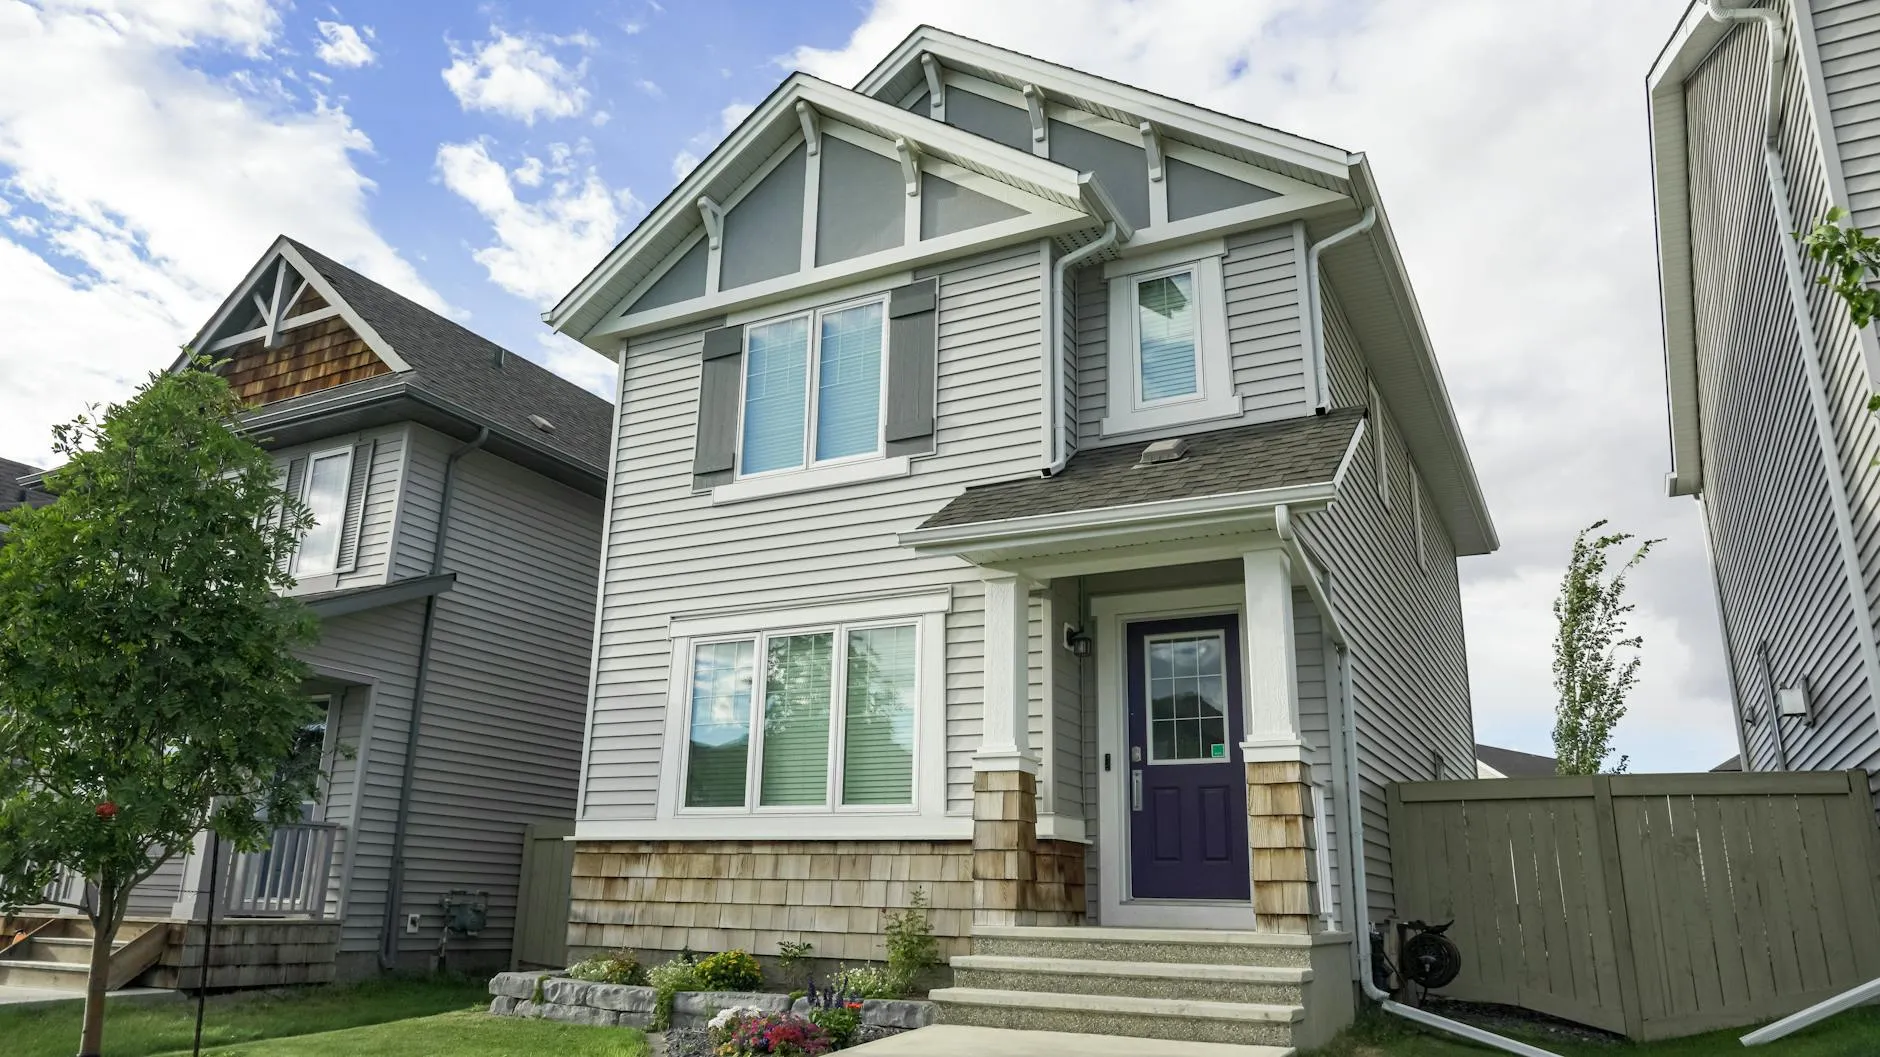
Coquitlam has grown from a Tri-Cities suburb into one of Metro Vancouver’s busiest markets for families and first-time buyers. The Evergreen Line put Burquitlam, Lougheed, Coquitlam Central, Lincoln and Lafarge Lake-Douglas within a SkyTrain ride of downtown, and most new condo supply has followed those stations. Up the hill, Westwood Plateau and Burke Mountain hold newer detached homes and townhouses, while Maillardville, Austin Heights and Central Coquitlam have older homes on larger lots, where BC’s small-scale multi-unit housing rules now allow extra units on many single-family properties.
Prices have softened over the past year. In August 2026, Greater Vancouver REALTORS put Coquitlam’s benchmark at about $1.6 million for a detached home, just under $1 million for a townhouse and about $646,000 for an apartment, each 6% to 9% lower than a year earlier. Those numbers shape your financing. A typical detached home now sits above the $1.5 million insured mortgage cap, so it needs at least 20% down. A typical townhouse can still be bought with less than 20% down, and a typical condo falls within BC’s first-time buyer property transfer tax exemption. Matching the right lender to that price point is the part I handle for you.
Coquitlam buyers are often juggling a presale deposit schedule, a suite that could help them qualify, or a renewal on a home they bought when rates were much lower. A broker gives you more than one bank’s rate. You get options from many lenders, flexibility, and advice shaped around your goals.
As your mortgage broker, I:
Because I’m based in Coquitlam and work here every week, I know which lenders are comfortable with Burke Mountain new builds, suite income on Westwood Plateau, and presale completions in Burquitlam, so you don’t have to learn that the hard way.
Explore mortgage services →
Understand your down payment options, BC programs, and the property transfer tax exemption that applies to most Coquitlam condos, then take the first step toward homeownership.
Start your mortgage checkup →
Many Coquitlam homeowners who locked in during 2020 and 2021 are now renewing at higher rates. Don’t sign your bank’s first offer. I’ll review it and compare competitive alternatives.
Access your home equity for a secondary suite, a laneway home, renovations, or debt consolidation, with a clear plan that makes sense for your situation.
Supportive and solution-focused refinancing options during separation or divorce.
Financing for Burke Mountain new builds, custom homes, multiplex projects, and major renovations on your own lot.
Tailored mortgage options for small business owners, contractors, and professionals with non-traditional income.
Programs designed to help newcomers to Canada buy a home, even without a long credit history.
View all services →
I help buyers and owners in every part of Coquitlam, from the SkyTrain corridor to the new communities up the hill:
Also serving nearby communities: Port Coquitlam, Port Moody, Burnaby, New Westminster, and the rest of the Lower Mainland.
It depends on the property type. At August 2026 benchmark prices, a typical Coquitlam condo around $646,000 needs a minimum of about $40,000 down, and a typical townhouse just under $1 million needs about $74,000. A typical detached home around $1.6 million is above the $1.5 million insured mortgage cap, so it needs at least 20% down, roughly $320,000. If you are buying purely as a rental, plan on at least 20% down whatever the price. I will confirm your exact numbers before you start shopping.
Run your own numbers with my BC down payment calculator →
Often, yes. Many Westwood Plateau and Burke Mountain homes include a secondary suite, and lenders can count part of that rent toward what you qualify for. The suite needs to be legal and documented, and each lender treats suite income differently, so I match your file to the lender that counts it most favourably.
Presales work differently from a resale purchase. You pay deposits during construction and arrange the mortgage closer to completion, which can be a year or more away. Buyers of newly built homes can qualify for a 30-year insured amortization, and a qualifying new build valued up to $1.1 million can be exempt from property transfer tax. I will plan your deposits, completion financing and rate strategy so there are no surprises on completion day.
Under BC’s small-scale multi-unit housing rules, many single-family lots in Coquitlam now allow additional units such as a suite, a laneway or carriage home, or a small multiplex, subject to city zoning and permits. Financing these projects usually means a construction or draw mortgage, or a refinance based on the value after completion. If you own in Maillardville, Austin Heights or Central Coquitlam and are thinking about adding units, I can walk you through the options.
These are real Google reviews from homeowners and buyers I have worked with. Read them all, or share your own experience, on my Google Business Profile.
Whether you’re planning your next move or just have questions, I’m here to help you make informed, confident mortgage decisions.
📞 778-882-5962
📍 Based in Coquitlam, serving the Tri-Cities and Metro Vancouver
Book a consultation →

